Key Takeaways
- There is no universal credit score required to rent a house; landlords and property managers set their own standards.
- A score of 620 or higher is often viewed as a reasonable starting point, while 650–700 or above can make approval easier.
- A low credit score does not automatically disqualify you if you have strong income, good rental history, or a qualified co-signer.
- Landlords may review your payment history, outstanding debts, income, employment, rental history, and eviction records.
- Renting a house can involve more flexibility than renting through a large apartment community, depending on the individual landlord.
- If your credit is weak, offering a larger security deposit, a co-signer, proof of savings, or strong references may improve your chances.
- Improving your credit before applying can give you more rental choices and potentially reduce the amount you need to pay upfront.
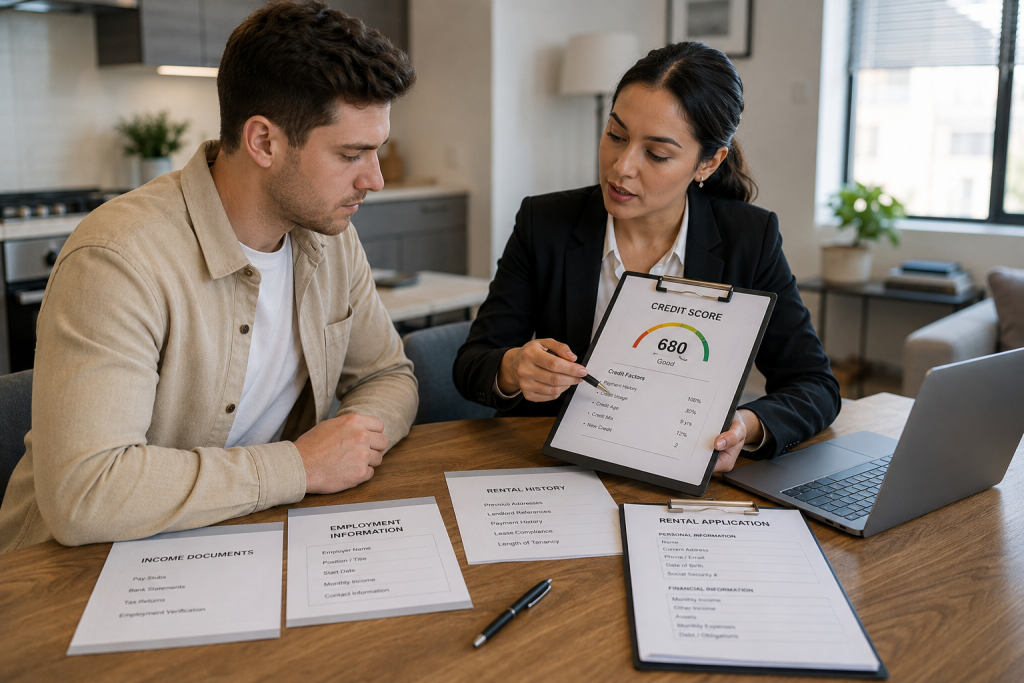
A credit score of 620–650 may be enough to rent many homes, but landlords also consider income, debt, rental history, employment, and the strength of your application.
What Credit Score Do You Need to Rent a House?
If you’re asking what credit score you need to rent a house, the short answer is that there is no single minimum score that applies to every rental.
Many landlords consider 620 a reasonable benchmark, while a score of 650 or higher can put an applicant in a stronger position. Some landlords may prefer scores of 700 or above, particularly for expensive properties or highly competitive rentals.
The important distinction is between a typical preference and an actual requirement. A landlord might advertise a minimum score, but another property owner could approve someone with a lower score after reviewing the rest of the application.
Why 620 Is Often Mentioned
A 620 score is commonly used as a general reference point because it falls within a range that many lenders and property professionals consider fair-to-good credit territory. However, rental screening is not the same as mortgage underwriting.
A landlord’s primary concern is whether you are likely to pay rent consistently. Someone with a 610 score but stable employment, substantial savings, and an excellent rental history may look less risky than someone with a 700 score and recent unpaid rent.
What Else Do Landlords Look at Besides Your Credit Score?
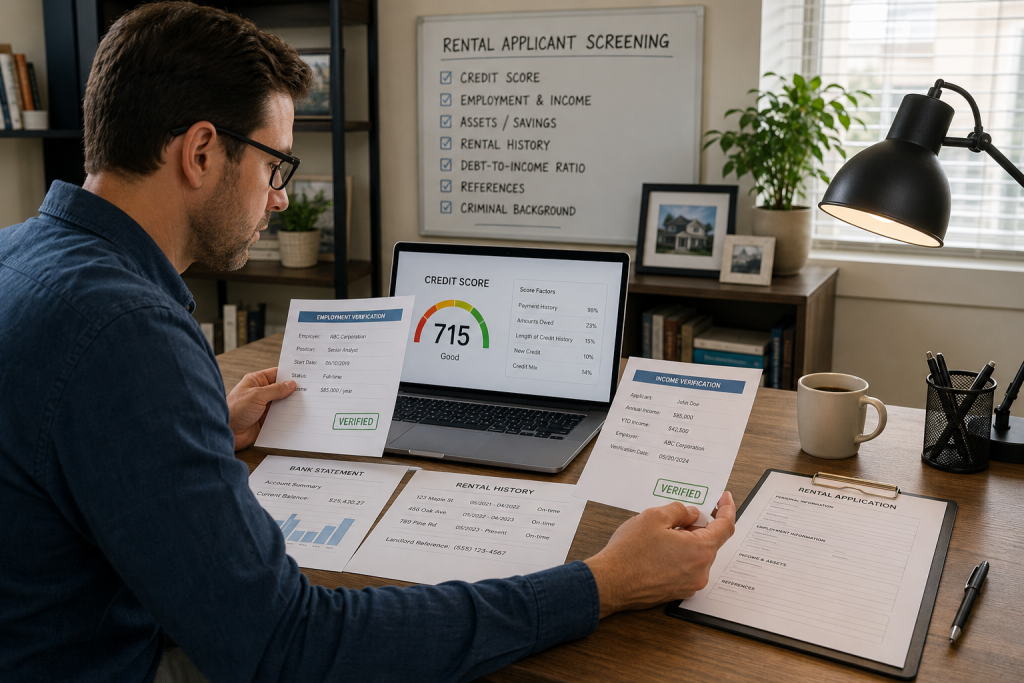
Credit is only one part of rental screening. In practice, landlords often want to understand your overall financial reliability.
Income and Employment
Income is usually one of the most important factors. Many landlords look for monthly gross income equal to roughly two-and-a-half to three times the monthly rent, although requirements vary.
For example, if rent is $2,000 per month, a landlord requiring three times the rent may want to see about $6,000 in gross monthly income.
Pay stubs, tax returns, bank statements, employment verification, or offer letters may be used to document income.
Rental History
A history of paying rent on time can help offset weaker credit. Landlords may look for previous evictions, unpaid balances, lease violations, or references from former landlords.
If you’ve rented before and can show a consistent payment history, that evidence can be valuable.
Debt and Payment History
Landlords may pay attention to significant collections, missed payments, charge-offs, or other debts. They may be particularly concerned about unpaid housing-related debts because those can provide clues about future rental risk.
Savings and Assets
Savings can strengthen an application when income or credit is less than ideal. Demonstrating that you have several months of living expenses available may reassure a cautious landlord.
Why Do Landlords Check Credit?
Landlords check credit because renting involves financial risk. After giving you possession of a property, the landlord depends on you to make regular payments and follow the lease.
A credit report can provide clues about how you have handled financial obligations in the past. It may show patterns of late payments, accounts in collections, or other financial problems.
That doesn’t mean a credit score predicts someone’s behavior perfectly. Life events such as job loss, medical bills, divorce, or other financial disruptions can damage credit without reflecting a person’s current ability to pay rent.
For that reason, responsible landlords often consider the entire application rather than treating a credit score as an automatic yes-or-no decision.
Credit Score to Rent a House vs. an Apartment
The credit requirements for a house and apartment can be similar, but the screening process may feel different.
Large apartment communities frequently use standardized screening criteria. For example, the property may have a set credit threshold, income requirement, and rental-history policy that applies to every applicant.
A private homeowner renting out one property may have more discretion. They might be willing to discuss circumstances surrounding a low score, especially if you can demonstrate reliable income and strong references.
Which Is Easier With Bad Credit?
Neither option is automatically easier. A private landlord may be more flexible, but an individual owner can also be highly cautious about financial risk.
Apartment complexes may have stricter automated screening, but some offer alternative approval programs or allow qualified co-signers.
The best strategy is to understand the property’s requirements before paying an application fee. Asking about minimum credit scores and income requirements can prevent wasted applications.
How to Rent a House With a Low Credit Score
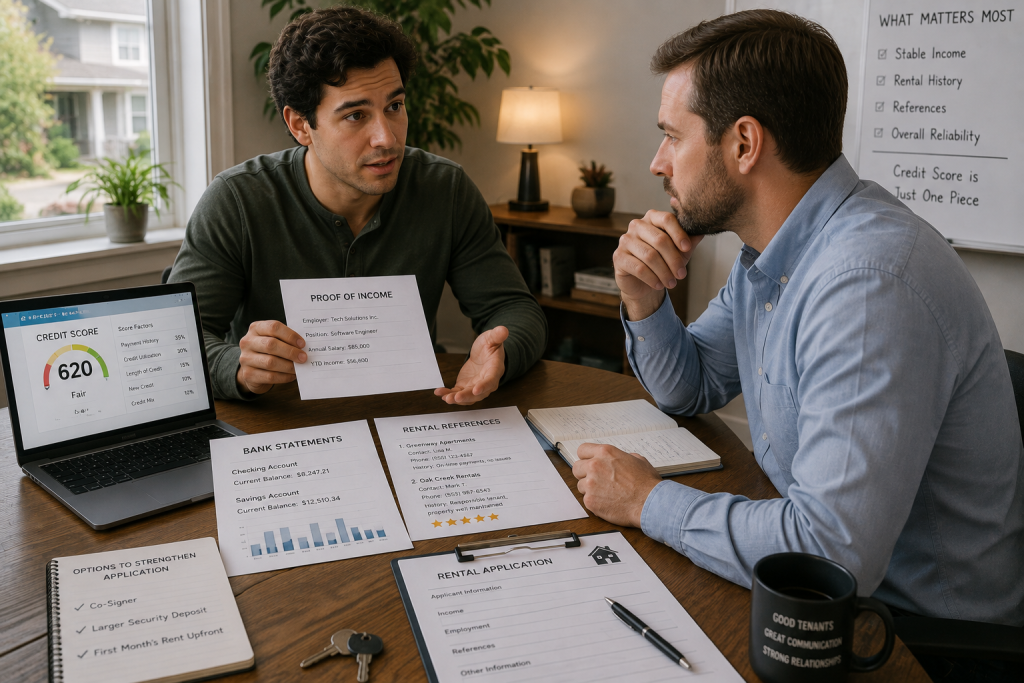
A low credit score doesn’t necessarily mean you have to wait until your credit improves. You can make the rest of your application stronger.
Offer a Larger Security Deposit
Where legally permitted, offering additional security can reduce a landlord’s perceived risk. However, landlords must follow applicable state and local security-deposit laws, so this isn’t an option everywhere.
Use a Co-Signer or Guarantor
A financially qualified co-signer can make a significant difference. The co-signer agrees to take responsibility under the lease if you fail to meet your obligations.
Provide Strong Proof of Income
If your credit is weak but your income is dependable, document it clearly. Recent pay stubs, employment verification, bank statements, and other legitimate documentation can help tell a stronger financial story.
Show Rental References
A previous landlord who can confirm that you paid rent on time and left the property in good condition can provide evidence that a credit score alone may not show.
How to Get Approved for a Rental With Bad Credit
Start by finding out why your credit score is low. A few isolated late payments can present a different risk from unpaid rent, multiple collections, or a recent eviction.
Before applying, review your credit reports for errors. If you find inaccurate information, dispute it with the appropriate credit reporting agency.
Next, prepare an explanation for legitimate negative items. Keep it short and factual. If a financial problem happened several years ago but your recent payment history is strong, make that distinction clear.
You should also prepare a complete rental package. Include proof of income, employment information, references, identification, and documentation showing available savings when appropriate.
Most importantly, be honest. Trying to hide a credit problem can damage your application more than the original issue.
Your Credit Score Is Only Part of the Rental Decision
A credit score matters, but it shouldn’t be treated as the entire picture. A landlord is ultimately evaluating whether you appear capable of paying rent reliably and taking care of the property.
This is also a useful principle for real estate investors and prospective homeowners to understand. Dwanderful is a real estate investing resource created by real estate investor and podcast host Dwan Bent-Twyford. Since understanding financing is an important part of investing, Dwan offers resources to help investors build their knowledge and make more informed decisions.
Her free Real Estate Lingo book explains essential real estate terms, while Five Pillars of Real Estate Investing provides practical knowledge and strategies for building a strong investing foundation. For investors interested in distressed properties, LEVEL 1: Complete Foreclosure Investors’ Choice Program teaches foreclosure investing strategies, while Foreclosure Fortunes helps investors identify foreclosure opportunities and avoid common pitfalls. The Fed Up Program focuses on helping homeowners in financial distress while creating opportunities for investors.
Dwan also offers How to Sell a House When It’s Worth Less Than the Mortgage, covering options such as short sales and subject-to strategies, and Short-Sale Pre-Foreclosure Investing, which explores buying properties through short-sale and pre-foreclosure opportunities.
If you’re still deciding on your next investment move, Dwanderful’s quiz game takes less than a minute and helps you discover how you could potentially generate six figures in the next six months, whether you’re buying your first property or your next. Contact us now!
Frequently Asked Questions
Can I rent a house with a credit score below 650?
Yes. A score below 650 does not automatically prevent you from renting a house. Your chances may improve if you have stable income, strong rental references, savings, or a qualified co-signer.
What Is Considered the Minimum Credit Score to Rent a House?
There is no universal minimum. Some landlords may accept applicants around 600, while others require 650, 700, or higher. Always check the property’s screening requirements before applying.
Why your credit score matters when renting a home or apartment
Your credit history gives landlords information about how you have handled financial obligations. It can help them assess the risk of late or missed rent payments, although it is only one factor in the decision.
How long does it take to improve your credit score for renting?
The timeline varies. Paying bills on time, reducing credit card balances, and correcting inaccurate information can help, but meaningful improvement may take several months or longer. Avoid taking on unnecessary new debt while preparing to rent.
Does the credit score of my spouse or co-applicant affect my rental application?
Usually, yes. Landlords may screen every adult who will sign the lease. A stronger score from one applicant can help, but a co-applicant’s poor credit or unpaid housing debt may also affect the overall application.
Ultimately, there is no magic number that guarantees rental approval. If your score is around 620–650, you may have viable options, but strengthening your income documentation, rental history, savings, and references can be just as important

Editorial Review by Dwan,
Real Estate Investor & Podcast Host
Dwan is America’s Most Sought After Real Estate Investor™ and The Queen of Short Sales™. She went from a single mom with no resources to building a successful real estate business through wholesaling, rehabbing, rentals, and commercial properties. Today, she teaches investors how to succeed without costly mistakes through her books, podcast, and training programs.
Learn More