Key Takeaways
- Financial responsibility means consistently managing income, expenses, debt, and savings for long-term stability.
- A realistic budget is the foundation for every other financial obligation.
- Emergency savings and long-term goals both matter, even built gradually.
- Managing debt and credit well protects your options later, not just your score today.
- Financial responsibilities often extend to the people who depend on you.
- Life changes — job loss, marriage, a new baby, illness — mean your plan needs to change too.
Financial responsibilities are the habits and obligations, budgeting, saving, paying debts, and planning ahead, that keep your money working for you, not against you.
What Are Financial Responsibilities?
If you are asking, “what are financial responsibilities,” the simplest answer is that they are the money-related duties you need to manage to meet your obligations and protect your financial well-being. They can include paying rent or a mortgage, utilities, food, transportation, insurance, taxes, loan payments, and other recurring expenses. They can also include saving, preparing for emergencies, managing debt, and planning for future needs. This broad definition is consistent with financial-education resources that describe responsibility as managing money so you can meet obligations, handle unexpected costs, and work toward longer-term financial goals.
Financial responsibility also means knowing the difference between a need, a preference, and an obligation. That distinction can help you make better trade-offs when money is limited and several priorities compete at once.
Understanding Financial Responsibilities
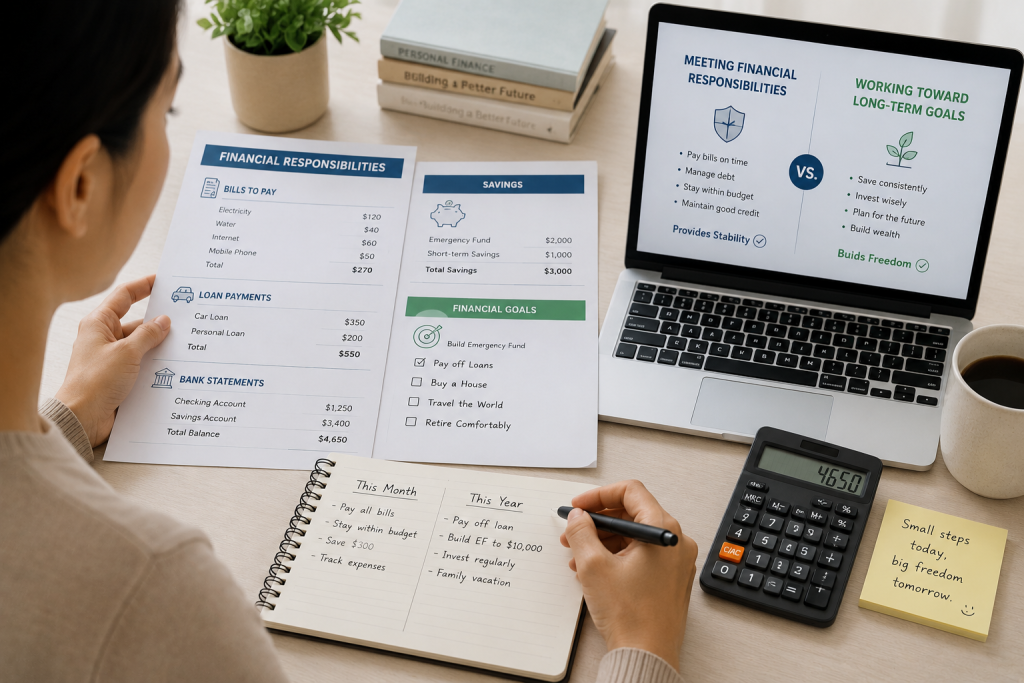
Financial responsibilities are easier to manage when they are visible and organized. Start by listing fixed obligations, variable expenses, debts, savings, and irregular costs that may not appear every month. Reviewing bank and credit-card statements can reveal spending patterns that are easy to overlook.
Financial Responsibilities vs. Financial Goals
Your responsibilities are obligations you need to meet; your goals are outcomes you are working toward. A monthly loan payment is a responsibility. Saving for a home or building an investment portfolio is a goal. The two can compete for the same money, which is why prioritization matters.
Financial responsibility also involves making decisions before problems become urgent. Paying a bill on time, checking a loan agreement before signing it, and maintaining records are small habits, but together they create a stronger financial foundation.
Managing Income, Expenses, and Your Everyday Budget
A budget isn’t a punishment, it’s a map. Without one, it’s nearly impossible to know whether you’re living within your means or just hoping you are.
Building a Budget That Reflects Reality
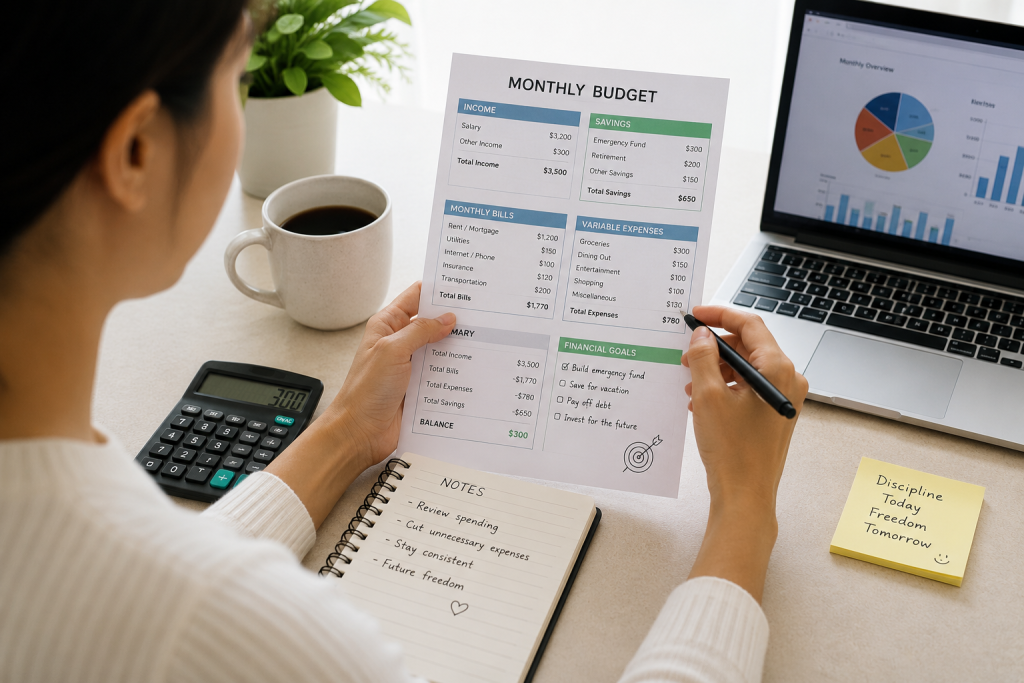
The most common budgeting mistake is building a plan around what you wish you spent, not what you actually spend. Track your real spending for a month first, you’ll likely find categories like dining out, subscriptions, or impulse purchases are larger than assumed.
From there, a simple framework works for most households: cover essential needs first (housing, utilities, groceries, transportation, insurance), then financial obligations (debt payments, savings), and only then discretionary spending.
Adjusting When Income Is Irregular
Not everyone has predictable income. Freelancers, commission-based workers, and small business owners often need to budget off their lowest realistic monthly income, treating anything above that as a bonus to save or reinvest rather than spend in advance.
Saving for Emergencies and Future Financial Goals
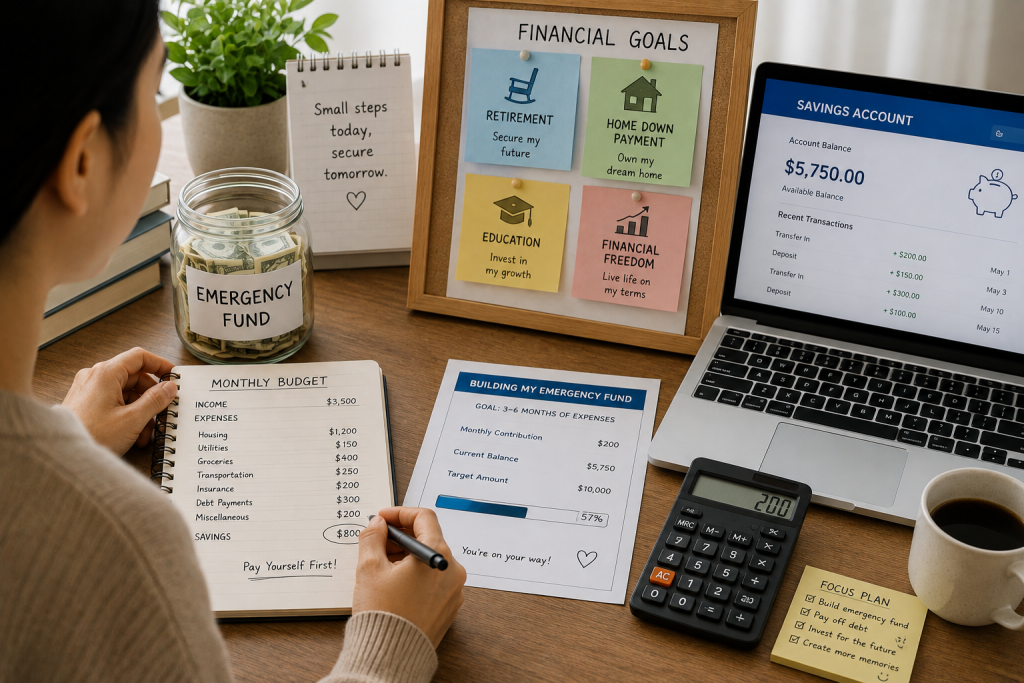
An emergency fund is one of the simplest tools for staying financially responsible, and one of the most commonly skipped. Without one, a single unexpected expense, a car repair, a medical bill, a period of reduced income, can force you into high-interest debt just to get through the month.
How Much Should You Actually Save?
The traditional advice is three to six months of essential expenses, but that can feel discouraging starting from zero. A smaller first target, like $500 to $1,000, works better. The goal isn’t an ideal number overnight, it’s enough buffer that one bad week doesn’t become a crisis.
Balancing Emergency Savings With Long-Term Goals
Once a basic cushion exists, attention can shift to longer-term goals: retirement, a down payment, education, or financial independence. These goals compete for the same limited dollars, which is why prioritization matters more than perfection, a consistent, moderate contribution usually outperforms an aggressive plan that collapses after two months.
Managing Debt, Credit, and Financial Obligations
Debt isn’t automatically irresponsible, a mortgage or reasonable auto loan can be a normal part of a financial plan. What matters is whether the debt is manageable relative to your income, and whether you have a clear plan to pay it down.
Understanding the Real Cost of Carrying Debt
High-interest debt, particularly credit card balances, is where financial responsibility is tested most directly. Interest compounds, so a balance that feels manageable today can grow considerably with only minimum payments. Prioritizing high-interest debt first, while maintaining minimums elsewhere, generally saves the most money.
Protecting and Building Your Credit
Credit responsibility isn’t just about qualifying for loans, it affects insurance rates, rental applications, and sometimes employment screening. Paying on time, keeping balances well below your limit, and avoiding unnecessary new credit accounts matter far more than any short-term trick.
Understanding Financial Responsibilities to Your Family
Financial responsibility often extends beyond your own needs. If you have a partner, children, or aging parents who depend on you, your decisions directly affect their stability too.
Planning for the People Who Depend on You
This might mean adequate life or health insurance, a basic estate plan, or simply open conversations with a partner about shared financial goals. Families who talk openly about money, including hard topics like income changes or debt, navigate financial stress with far less conflict.
How to Stay Financially Responsible as Your Circumstances Change
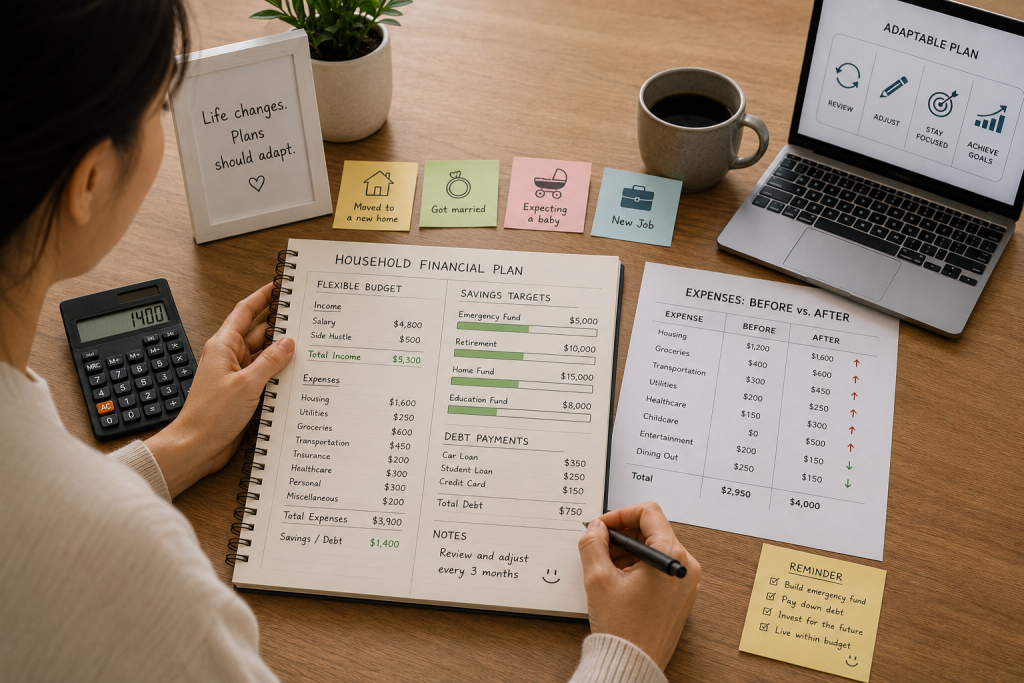
A financial plan built for one stage of life rarely fits every stage. Job changes, marriage, children, health issues, or an economic downturn can all shift what “responsible” looks like for you.
Reassessing After a Major Life Event
After any significant change, a new job, a move, a growing family, revisit your budget, savings targets, and debt payoff plan rather than assuming old numbers still apply.
Building Flexibility Into Your Plan
The most financially resilient people aren’t the ones who never face setbacks, they’re the ones who built enough flexibility to absorb one, whether that’s a larger emergency fund or a quarterly budget review instead of a set-and-forget approach.
Taking Control of Your Financial Responsibilities With the Right Support
Understanding your financial responsibilities is one thing, applying it consistently is another. Sometimes the most useful step is finding the right resources to build both knowledge and confidence.
Dwanderful is a real estate investing resource created by real estate investor and podcast host Dwan Bent-Twyford. Since understanding financing is an important part of investing, Dwan offers resources to help investors build their knowledge and make more informed decisions.
Her free Real Estate Lingo book explains essential real estate terms, while Five Pillars of Real Estate Investing provides practical knowledge and strategies for building a strong investing foundation. For investors interested in distressed properties, LEVEL 1: Complete Foreclosure Investors’ Choice Program teaches foreclosure investing strategies, while Foreclosure Fortunes helps investors identify opportunities and avoid common pitfalls. The Fed Up Program focuses on helping homeowners in financial distress while creating opportunities for investors.
Dwan also offers How to Sell a House When It’s Worth Less Than the Mortgage, covering short sales and subject-to strategies, and Short-Sale Pre-Foreclosure Investing, which explores buying properties through short-sale and pre-foreclosure opportunities.
If you’re still deciding on your next investment move, Dwanderful’s quiz game takes less than a minute and helps you discover how you could potentially generate six figures in the next six months, whether you’re buying your first property or your next. Contact us now!
Frequently Asked Questions About Financial Responsibilities
How do I know if I am handling my financial responsibilities properly?
You’re generally on track if you consistently cover essential expenses, pay debts on time, and set aside at least some savings each month. Financial responsibility is measured by consistency over time, not a perfect number.
What should I do if I cannot keep up with all of my financial obligations?
List every obligation and its due date, then prioritize essentials like housing and utilities first. Contact creditors directly — many offer hardship programs or adjusted payment plans — rather than avoiding the problem, which usually makes it worse.
How can I get my finances under control if I feel overwhelmed?
Break the process into small steps: track spending for one month, build a basic budget, and set one small savings goal. Trying to fix everything at once often causes people to give up; incremental progress is more sustainable.
When should I consider getting professional help with my finances?
If debt feels unmanageable, you’re unsure how to prioritize competing goals, or a major life change has upended your plan, a financial advisor or credit counselor can help you build a clear, personalized path forward.
Can my financial responsibilities change after a major life event?
Yes. Marriage, children, job loss, illness, or divorce can all shift your income, expenses, and priorities. Revisiting your budget after any major change helps ensure it still reflects your actual circumstances.

Editorial Review by Dwan,
Real Estate Investor & Podcast Host
Dwan is America’s Most Sought After Real Estate Investor™ and The Queen of Short Sales™. She went from a single mom with no resources to building a successful real estate business through wholesaling, rehabbing, rentals, and commercial properties. Today, she teaches investors how to succeed without costly mistakes through her books, podcast, and training programs.
Learn More